
How Financial Centers Sell Law, Tax Neutrality, and Trust
Some countries export oil, machinery, or software. Financial centers export something less visible: a legal address that global money is willing to trust.
A fund may be incorporated in the Cayman Islands, managed from London, administered in Dublin, keep its securities with a custodian in New York, and accept investors from Singapore. Billions of dollars can be organized through a jurisdiction even when the cash, employees, investment decisions, and underlying assets are somewhere else.
This is the strange geography of modern finance. Money does not always travel to the place printed on the legal documents. Often, what moves is the contract.
What does “offshore” actually mean?
At its simplest, offshore finance means providing financial services to nonresidents. A bank in one jurisdiction takes deposits from people elsewhere, lends to borrowers elsewhere, or books transactions whose commercial life largely occurs beyond its borders.
The word sounds as if it describes an island. It does not. London, New York, Singapore, Luxembourg, Dubai, the Cayman Islands, and Switzerland all handle cross-border business, but they do not belong to one neat category.
An international financial center such as London has deep markets, major banks, payment and settlement systems, professional services, and a large domestic economy. A regional center such as Dubai or Singapore channels money into and out of a wider region. A classic offshore center may have a financial sector vastly larger than its domestic economy and specialize in entities, funds, trusts, insurance, or transactions created mainly for nonresidents.
The boundary is blurred. “Offshore” is less a map coordinate than a relationship: the customer, assets, liabilities, or controlling parties are somewhere else.
What these places are really selling
A successful financial jurisdiction does not primarily sell office space. It sells a package of institutional promises.
First comes law. Investors want to know how contracts will be interpreted, which court will hear a dispute, whether collateral can be enforced, what happens in insolvency, and whether a judgment will be recognized elsewhere.
Second comes regulation. A credible license, respected supervisor, and familiar rulebook can make an entity acceptable to banks, institutional investors, auditors, and counterparties. Too little regulation creates suspicion. Too much uncertainty creates cost.
Third comes tax treatment. The most useful structure is often not one that eliminates all tax, but one that avoids charging an extra layer merely because investors have pooled their money through a common vehicle.
Then comes the ecosystem: lawyers, accountants, administrators, trustees, corporate service providers, banks, custodians, exchanges, data centers, and regulators who understand the same structures. Once that network becomes dense, it is difficult for a competing jurisdiction to reproduce.
Finally comes reputation. A contract governed by an unfamiliar legal system may be perfectly valid, yet still unacceptable to an investment committee. Familiarity reduces the amount of explaining required before money can move.
The City of London is not a separate offshore country
The City of London is frequently described as if it were a sovereign financial enclave hidden inside Britain. It is not.
The Square Mile is an unusually old municipal jurisdiction with its own corporation, Lord Mayor, electoral arrangements, and police force. Its civic privileges predate the modern British state. But companies operating there remain subject to UK law, taxation, financial regulation, courts, and national policy. The City is not a tax-exempt country within a country.
Its financial power grew from accumulated advantages: English commercial law, maritime trade, insurance, banking expertise, a time zone bridging Asia and North America, global use of English, deep capital markets, and a huge concentration of professional talent.
London illustrates an important point. A financial center does not need low taxes or secrecy to attract international money. Liquidity, enforceable contracts, skilled intermediaries, and the ability to complete a complicated transaction quickly may be more valuable than a lower tax rate.
DIFC: a legal operating system built inside Dubai
Dubai International Financial Centre is a different creature. It was deliberately constructed as a financial free zone and an independent jurisdiction within the United Arab Emirates for civil and commercial matters.
DIFC has its own body of commercial laws, a framework based on common-law principles, its own courts, and a dedicated financial regulator, the Dubai Financial Services Authority. It is not a sovereign country, and its jurisdiction is limited, but within that boundary it gives international firms a legal environment that feels familiar to investors accustomed to common-law finance.
This is institutional engineering. Rather than waiting centuries for commercial customs to evolve, Dubai built a specialized operating system: recognizable courts, English-language documentation, financial regulation, foreign ownership, and an ecosystem aimed at business spanning the Middle East, Africa, and South Asia.
The attraction is not simply a favorable tax environment. It is the ability to place a transaction in a framework that global banks, investors, insurers, and law firms already know how to evaluate.
Luxembourg: the cross-border fund factory
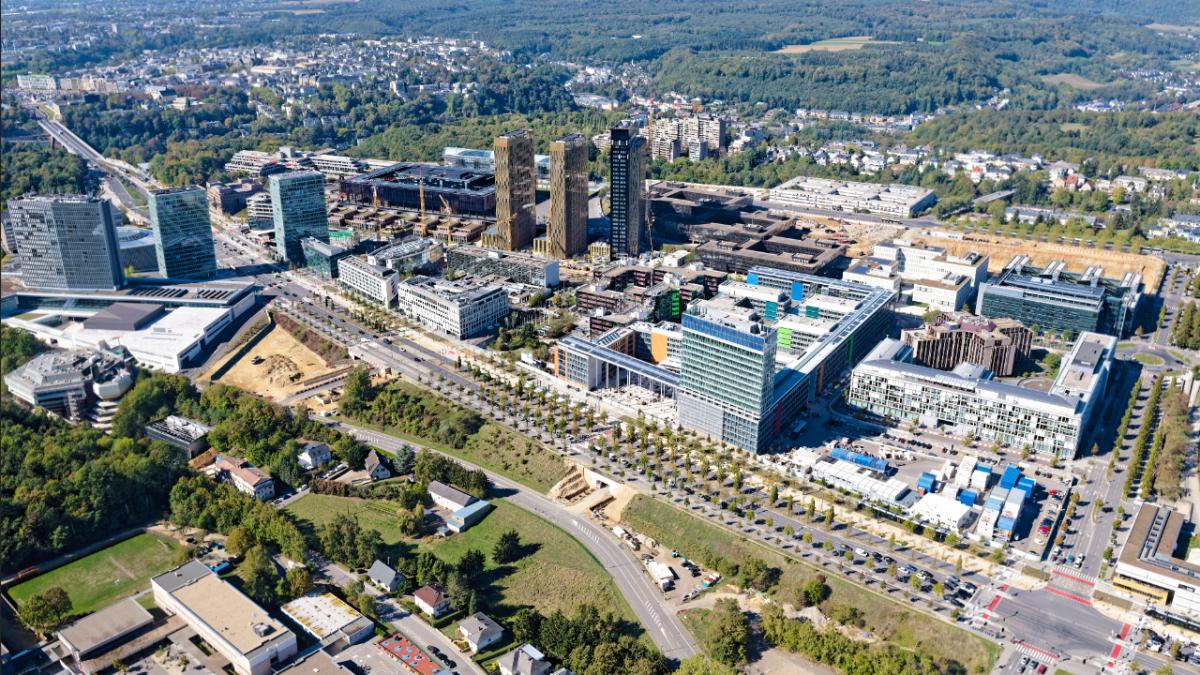
Luxembourg demonstrates another model. It is not an unregulated offshore island; it is an EU member state whose financial industry specializes in creating regulated products for investors across borders.
Suppose an asset manager wants one investment fund that can be marketed in several European countries. Domiciling it in Luxembourg may provide a familiar legal form, an experienced regulator, fund administrators, depositary banks, auditors, multilingual documentation, and access to European distribution arrangements.
The fund’s portfolio might contain American equities, Asian bonds, or global infrastructure. Its investment team may sit in Paris or London. Yet the fund itself is Luxembourgish because Luxembourg supplies the legal shell, oversight, administration, and distribution architecture.
This is why a small country can appear to host an astonishing quantity of financial assets. The assets are not necessarily piled inside local bank vaults. Luxembourg is the legal and operational home from which claims on assets around the world are organized.
Cayman: the neutral meeting room
The Cayman Islands are widely associated with hedge funds and offshore companies. The caricature is a beach, a brass plate, and hidden money. The reality is more complicated.
A Cayman fund can act as a neutral pooling vehicle for investors from several countries. The manager may be in the United States, the administrator in Ireland, the prime broker in London, and the portfolio held through global custodians. Cayman supplies the entity law, fund regime, service providers, and regulatory framework through which those relationships are assembled.
Neutrality matters when investors do not want the pooled vehicle itself to impose an additional corporate tax layer before returns reach them. That does not automatically make the investors tax-free. Their obligations may arise where they live, where the manager operates, where income is earned, or where controlled-foreign-company and anti-avoidance rules apply.
Cayman’s financial system is also regulated. Investment funds, banks, trust companies, and securities businesses fall within legal and supervisory regimes administered by the Cayman Islands Monetary Authority. The serious question is therefore not whether regulation exists, but whether the structure has adequate transparency, substance, supervision, and economic purpose.
Tax neutrality is not the same as tax exemption
This distinction is where public arguments about offshore finance often collapse.
A tax-neutral fund aims to avoid adding an extra tax merely because investors pooled capital through an intermediary. Imagine investors in five countries buying assets in ten others. If the fund vehicle pays full corporate tax and every investor is then taxed again at home, the structure may create taxation that direct investment would not have produced.
A neutral vehicle tries to pass investment outcomes through without becoming an unnecessary tax tollbooth. Investors may still owe income tax, capital-gains tax, withholding tax, estate tax, or other charges in the relevant jurisdictions.
Tax evasion is different. It involves unlawfully hiding income, assets, ownership, or transactions to escape tax that is legally due. Tax avoidance uses legal arrangements to reduce tax, although aggressive avoidance may be challenged under anti-abuse rules. Tax planning ranges from ordinary and expected to highly artificial.
The address alone does not decide which category applies. The purpose, ownership, cash flows, management, disclosure, substance, and applicable laws do.
Secrecy is no longer the product it once was
Offshore centers historically competed partly through confidentiality and limited disclosure. That world has narrowed.
Under the OECD’s Common Reporting Standard, participating jurisdictions require financial institutions to collect information about certain foreign account holders and exchange it annually with relevant tax authorities. FATF standards push jurisdictions to identify the real people who ultimately own or control companies and legal arrangements.
These systems are imperfect. Registers can contain stale information, ownership can be layered, enforcement varies, and determined criminals seek gaps. But the idea that an offshore account is automatically invisible to the account holder’s home government is increasingly obsolete.
For legitimate clients, the competitive product has shifted from secrecy toward administratively efficient, internationally recognized structuring. For illegitimate clients, opacity remains attractive—but it also creates the banking, regulatory, and criminal risk that can contaminate everyone using the same jurisdiction.
Where is the money, really?
One of the most useful questions in cross-border finance is also one of the simplest: when someone says that US$500 million is “in” Luxembourg or Cayman, what exactly is there?
It may be the legal entity. It may be the shareholder register, fund documents, accounting records, board, administrator, or regulatory relationship. The bank deposit may be in London. The securities may be recorded at a global custodian in New York. The investment manager may give instructions from Hong Kong. The underlying asset may be an airport in Spain.
Financial geography has layers: legal domicile, tax residence, management location, bank-account location, custody location, investor location, asset location, and regulatory perimeter. They can all be different.
This is why a structure diagram often explains more than a corporate address. The address tells you where the legal wrapper lives. It does not tell you where the economic activity occurs.
Where financial centers help—and where they create danger
Specialized centers can make global investment easier. They standardize documents, pool investors, reduce duplicate tax layers, provide neutral courts, create specialist jobs, and connect capital with projects that might otherwise struggle to attract it.
They can also enable regulatory arbitrage: placing an activity where the rules are lighter while selling into markets where the consequences appear. Complex chains can obscure ownership, shift profits away from the places where business occurs, complicate insolvency, and frustrate law enforcement.
There is also a banking problem. A company may be legally incorporated and properly licensed yet still struggle to open an account because its jurisdiction, ownership chain, or business model exceeds a bank’s risk appetite. A structure optimized only for tax may be commercially useless if banks, investors, payment partners, or regulators refuse to touch it.
The strongest jurisdiction is therefore not necessarily the one with the lowest headline tax rate. It is the one whose legal, tax, regulatory, banking, and reputational pieces fit the actual transaction.
The address is part of the product
A financial center succeeds when the world believes that its promises will travel: its contracts will be enforced, its entities recognized, its records trusted, and its judgments respected.
London accumulated that confidence over centuries. Dubai built a specialized common-law platform inside a civil-law federation. Luxembourg industrialized the cross-border investment fund. Cayman became a widely used domicile for internationally pooled capital.
They are not interchangeable, and calling all of them “tax havens” hides more than it reveals.
The modern financial center is a jurisdiction factory. Its export is not money itself. Its export is the legal and institutional container that allows money owned in one country, managed in another, invested in a third, and reported in a fourth to be treated as one coherent transaction.
Important sources
International Monetary Fund, Offshore Financial Centers — Background Paper: https://www.imf.org/external/np/mae/oshore/2000/eng/back.htm
Dubai International Financial Centre, Laws and Regulations: https://www.difc.com/business/laws-and-regulations
City of London Corporation, Our Role in London: https://www.cityoflondon.gov.uk/about-us/about-the-city-of-london-corporation/our-role-in-london
Commission de Surveillance du Secteur Financier, Investment Vehicles and Investment Fund Managers: https://www.cssf.lu/en/investment-vehicles-and-investment-fund-managers/
Cayman Islands Monetary Authority, Investment Funds: https://www.cima.ky/investment-funds
OECD, International Standards on Tax Transparency: https://www.oecd.org/en/topics/sub-issues/international-standards-on-tax-transparency.html
Financial Action Task Force, Beneficial Ownership: https://www.fatf-gafi.org/en/topics/beneficial-ownership.html