
When you send money from New York to London, it feels as though your dollars leave the United States, cross the Atlantic, and arrive in the United Kingdom. That is a useful mental picture, but it is not how most cross-border payments actually work.
The money itself does not travel from one country to another like a package. What moves across the payment system is primarily information: payment instructions, account information, settlement messages, and confirmations. Banks and other financial institutions then change the balances recorded on their respective ledgers.
The simplest way to understand a cross-border payment is this:
Information moves. Ledgers change. The payment is the coordinated result.
The infographic illustrates this using a simple example: Alice in New York sends US$100 to Bob in London.
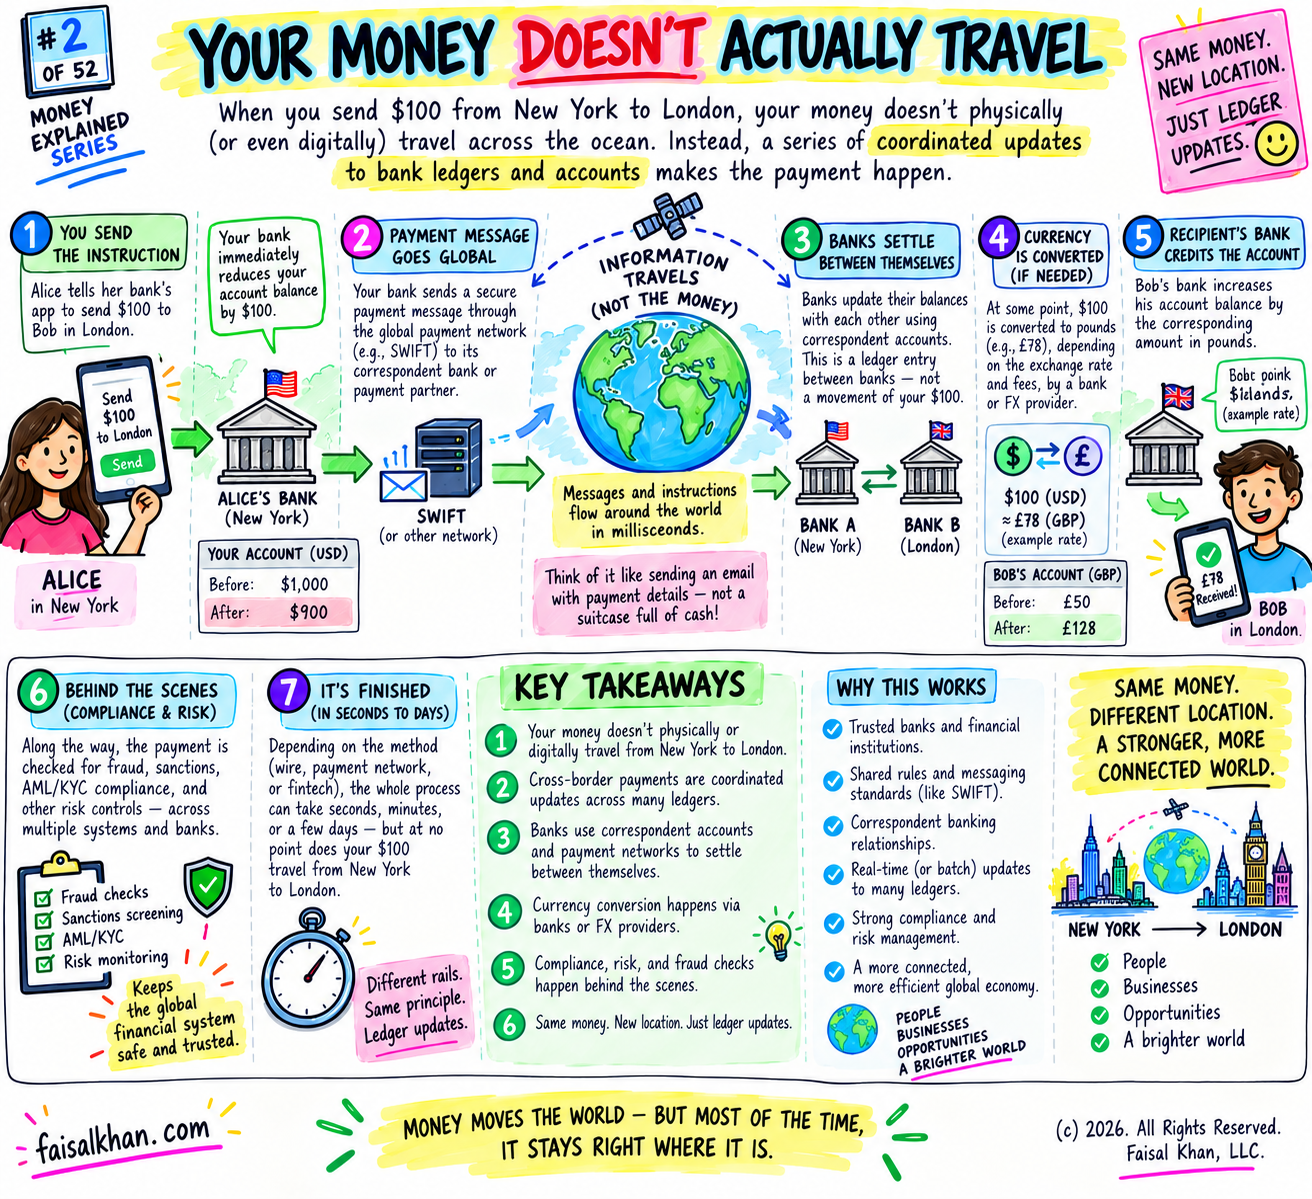
Start With Two People and Two Bank Accounts
Alice has money recorded in her account at a bank in New York. Bob has an account at a bank in London.
Suppose Alice's balance is US$1,000 and she wants to send US$100 to Bob.
Alice does not have to identify which dollars in her account should be sent. There are no particular digital dollar bills sitting inside her account waiting to be transported.
Her US$1,000 balance is a record maintained on her bank's ledger. When she initiates the payment, she is instructing her bank to change that record and arrange corresponding changes elsewhere in the financial system.
That distinction is fundamental to understanding modern payments.
Step 1: Alice Gives Her Bank a Payment Instruction
Alice begins by telling her bank to send US$100 to Bob.
She might do this through a banking app, online banking portal, payment company, remittance service, or another payment interface.
The instruction contains the information required to identify the payment and its destination. Depending on the payment method, that can include the recipient's name, bank, account details, amount, currency, and other transaction information.
At this point, what has started moving through the financial system is an instruction.
The US$100 has not flown out of New York.
Step 2: Alice's Bank Debits Her Account
Alice's bank updates its own ledger.
If Alice started with US$1,000 and sends US$100, her account may now show:
Alice's Account | Balance |
|---|---|
Before payment | US$1,000 |
Payment | -US$100 |
After payment | US$900 |
This is an accounting change inside Alice's bank.
The bank has changed what its records say it owes Alice. Her balance has decreased by US$100.
This is the first important ledger update in the payment.
Step 3: The Bank Sends Payment Messages
Alice's bank now needs to communicate with the institutions involved in getting value to Bob's bank.
Banks and payment providers use payment networks and messaging systems to exchange instructions and transaction information. In traditional correspondent banking, this can involve SWIFT messages and one or more intermediary or correspondent banks.
A payment message and settlement are related, but they are not the same thing.
The message communicates what should happen.
The settlement process determines how the financial obligations between participating institutions are discharged.
This distinction is important because a payment can involve messages moving almost instantly while the associated settlement follows a different process or timetable.
Step 4: Banks Adjust Balances Between Themselves
This is the part that often creates confusion.
Banks maintain accounts and financial relationships with other banks. In correspondent banking, these can include accounts held with correspondent institutions in currencies and financial centers relevant to the payment.
Instead of Alice's particular US$100 traveling across the Atlantic, institutions make accounting entries against balances they already maintain with one another.
Conceptually, imagine several interconnected spreadsheets.
One spreadsheet says how much Alice's bank owes Alice.
Another records balances between financial institutions.
Another records how much Bob's bank owes Bob.
The payment works because the appropriate institutions agree on the transaction and update those records consistently.
This is why correspondent banking relationships and settlement accounts are so important to traditional cross-border payments.
Step 5: Currency Conversion May Take Place
Alice is sending dollars, but Bob may need to receive pounds sterling.
Somewhere in the payment chain, the currency therefore has to be converted.
For example:
US$100 → GBP at the applicable exchange rate → amount credited in GBP
The foreign exchange conversion might be performed by Alice's bank, Bob's bank, a correspondent bank, a payment provider, or another FX provider involved in the transaction.
The exchange rate, spread, and fees determine how much Bob ultimately receives.
Again, the useful mental model is not that a US$100 digital object reaches London and transforms itself into pounds.
Instead, the institutions involved calculate the currency conversion and make the appropriate entries in the relevant currency accounts and ledgers.
Step 6: Bob's Bank Credits Bob's Account
Once Bob's bank has the necessary payment information and the applicable settlement conditions have been satisfied, it updates Bob's account.
Suppose Bob previously had £20 and the payment results in a £78 credit.
Bob's Account | Balance |
|---|---|
Before payment | £20 |
Incoming payment | +£78 |
After payment | £98 |
From Bob's perspective, the money has "arrived."
What actually happened is that Bob's bank changed its ledger to show that it now owes Bob an additional £78.
Bob can see the result because his account balance has changed.
Step 7: Alice and Bob See Different Sides of the Same Payment
Alice sees a US$100 debit.
Bob sees a credit in pounds.
Those two visible account changes are connected by a larger chain of payment instructions, interbank balances, settlement arrangements, foreign exchange activity, and ledger entries.
This is why a cross-border payment should be understood as a coordinated financial process, rather than as a piece of money traveling from Point A to Point B.
The user experience makes the payment look simple. The infrastructure underneath it can be considerably more complex.
Step 8: Compliance, Risk, and Reconciliation Happen Behind the Scenes
The infographic also highlights an important part of the process that customers rarely see.
Cross-border payments can pass through multiple operational and compliance controls. Depending on the institutions, jurisdictions, payment type, and risk profile, these can include:
customer identification and KYC controls;
AML monitoring;
sanctions screening;
fraud detection;
transaction monitoring;
fee calculations;
foreign exchange calculations;
payment routing;
reconciliation; and
exception handling.
These activities can occur across several institutions and systems.
This helps explain why two payments that look identical to a customer can follow different routes, incur different costs, or take different amounts of time to complete.
Step 9: The Payment Is Complete
Eventually, Alice sees the debit and Bob sees the credit.
The payment may have taken seconds, minutes, hours, or longer depending on the payment rail, institutions, currencies, jurisdictions, compliance requirements, settlement model, and intermediaries involved.
But there was never a moment when Alice's specific US$100 existed as a digital bundle traveling somewhere over the Atlantic.
Instead, the system coordinated a series of instructions and accounting changes until the relevant institutions' records reflected the completed transaction.
Think of Cross-Border Payments as Interconnected Ledgers
A useful simplification is to imagine the global banking system as a collection of interconnected spreadsheets.
Each institution maintains its own records.
When a payment occurs, those records have to be updated in a coordinated way.
For our simplified example:
Alice's bank reduces Alice's balance.
Payment instructions are transmitted.
Banks account for obligations between themselves.
Foreign exchange may convert the value from USD to GBP.
Bob's bank increases Bob's balance.
The participating institutions reconcile their records.
No single spreadsheet controls the entire transaction.
The payment works because the institutions, payment networks, settlement arrangements, rules, and ledgers interact with one another.
Messaging Is Not the Same as Money Movement
One of the most important concepts in payments is the difference between payment messaging and settlement.
A payment message can tell another institution:
Credit this beneficiary according to these payment instructions.
But the message itself is not the money.
The institutions still need a mechanism for settling the financial obligation created by the transaction.
This is one reason payment systems can be confusing from the outside. A message may travel almost instantaneously while settlement follows separate rules.
Understanding this distinction makes concepts such as correspondent banking, clearing, settlement, prefunding, nostro and vostro accounts, and payment rails much easier to understand.
So, Does Money Move at All?
In everyday language, saying that "money moved from New York to London" is perfectly understandable.
Operationally, however, it is more precise to say that value was transferred through coordinated changes in financial claims and account balances.
Settlement assets can move between institutions or settlement accounts, depending on the architecture of the payment system. But this is different from imagining Alice's individual US$100 traveling intact from her account in New York into Bob's account in London.
The infographic deliberately simplifies the machinery to make this distinction clear.
The essential idea remains:
Your money doesn't travel the way you imagine it does. The financial system changes records so that value is transferred from one party to another.
Why This Matters
Once you understand that payments are fundamentally about ledgers, messaging, settlement, and reconciliation, many apparently complicated parts of banking become easier to understand.
It becomes clearer why banks need correspondent relationships. It becomes clearer why liquidity must be available in particular currencies and locations. It becomes clearer why payment companies maintain prefunded balances. And it becomes clearer why a transaction can be successfully instructed but still encounter delays during compliance, settlement, or reconciliation.
The visible payment is only the final result of a much larger coordination problem.
Key Takeaways
Your specific dollars do not physically or digitally travel from New York to London.
A bank account balance is a ledger record representing a financial claim.
Cross-border payments involve coordinated updates across multiple accounts and ledgers.
Payment messages communicate instructions; they are not themselves the money.
Banks may use correspondent accounts and other settlement arrangements to discharge obligations between institutions.
Currency conversion changes the denomination of value when the sender and recipient use different currencies.
AML, KYC, sanctions, fraud, risk, and reconciliation processes can operate behind the scenes.
What the sender experiences as "money sent" and the recipient experiences as "money received" is the visible outcome of these coordinated processes.
Frequently Asked Questions
Does money physically move when I make an international transfer?
Normally, no physical cash travels from the sender's country to the recipient's country. The transaction is executed through payment instructions, settlement arrangements, and changes to account balances maintained by financial institutions.
Does digital money travel from one bank to another?
Not in the way a digital file moves from one computer to another. Banks maintain their own ledgers and accounts. Payment and settlement systems coordinate the changes necessary for the participating institutions to recognize the transfer of value.
What actually travels across borders?
Primarily information: payment instructions, account information, transaction data, confirmations, compliance information, and other messages required to process the payment.
What is correspondent banking?
Correspondent banking is an arrangement in which one financial institution provides banking services to another, often including accounts used to facilitate payments and settlement in particular currencies or jurisdictions. Correspondent relationships are an important part of many traditional cross-border payment flows.
Is SWIFT the system that moves the money?
SWIFT is principally a financial messaging network. It allows financial institutions to exchange standardized messages securely. The associated financial obligations still need to be settled through accounts and settlement arrangements.
Why does an international payment sometimes take several days?
Timing depends on the payment rail, currencies, banks, intermediaries, time zones, cutoffs, compliance checks, settlement arrangements, and whether manual intervention or exception handling is required.
Where does foreign exchange happen?
It can occur at different points in the transaction. The conversion may be performed by the sending bank, receiving bank, correspondent bank, payment provider, or another FX provider.
Why do payment companies prefund accounts?
Prefunding places liquidity where payouts or settlement will be required. This can allow a provider to credit recipients using balances already available in the destination market rather than waiting for every individual transaction to trigger a separate movement of settlement liquidity.
Copyright 2026, all rights reserved, Faisal Khan LLC