
Part of our POBO & COBO Solutions guide.
The Problem
The phrase 'on behalf of' can create a dangerous false sense of exemption. In the United States, a business that accepts, holds, or transmits money for unrelated customers can face federal MSB and state money-transmission questions even if the commercial team calls the model POBO or COBO.
The correct design starts with the flow of funds: who owns the funds, who owes or is owed money, who owns the external bank account, what the relationship is between the parties, and whether the underlying parties are related group companies or external customers.
Typical Flow
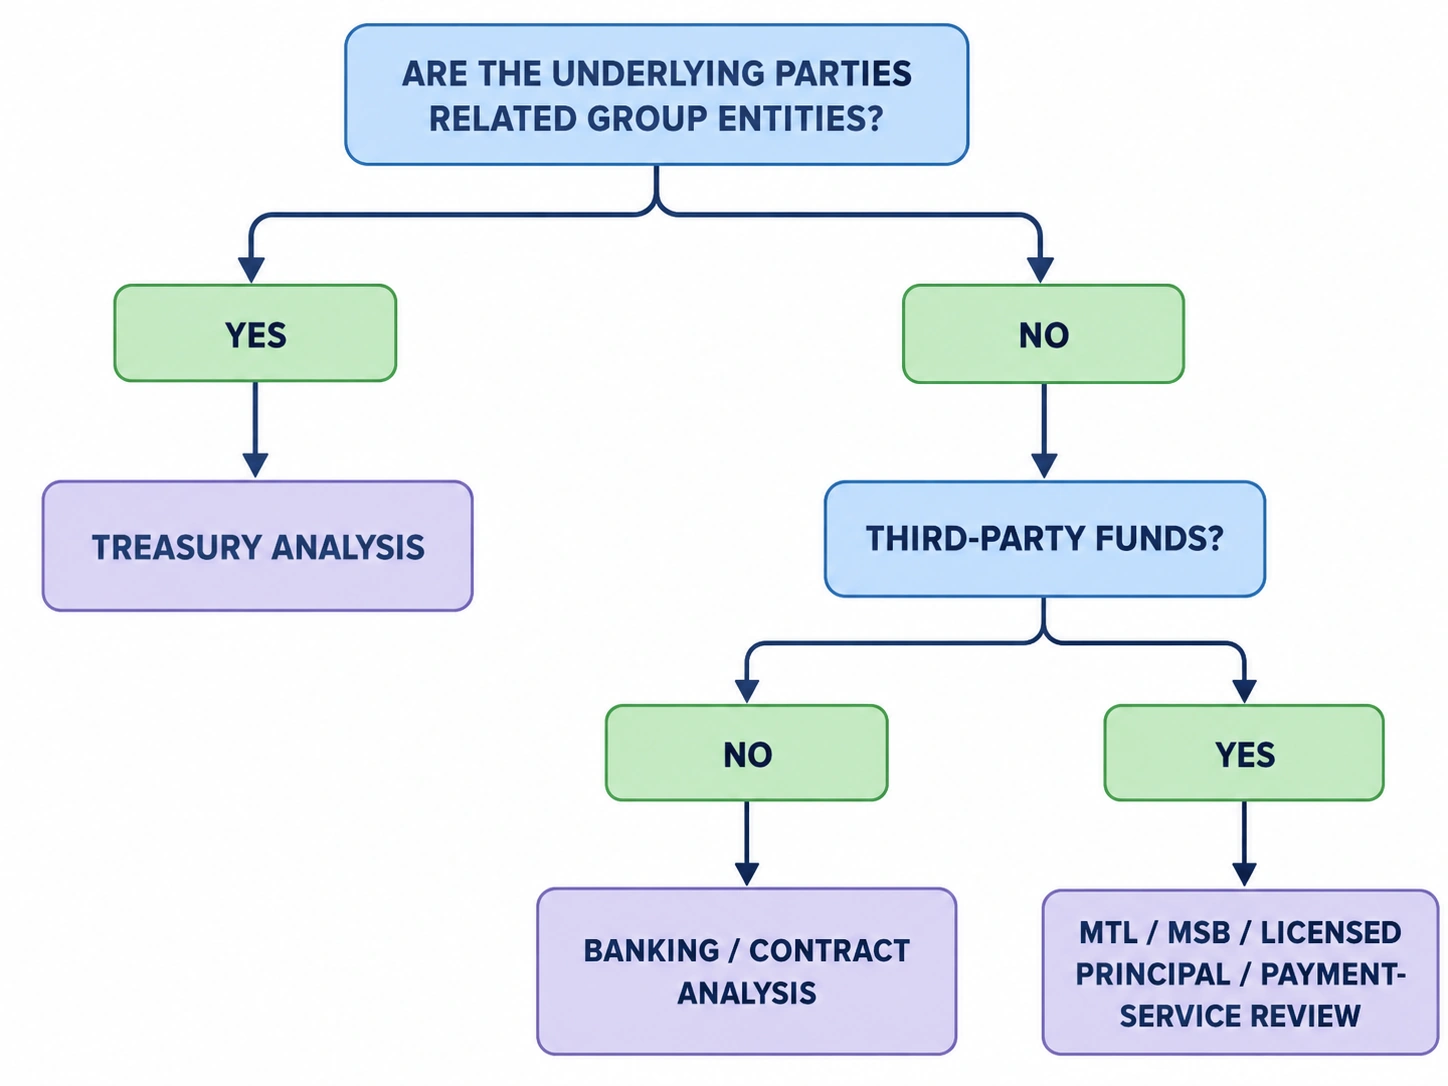
The diagram is intentionally generic. Actual implementation depends on the legal entities, jurisdictions, bank/provider rules, payment rails, currencies, licensing status, and reconciliation model.
Own/Group Funds vs Third-Party Funds
The distinction is critical. Paying obligations within a corporate group is different from taking customer funds and paying unrelated beneficiaries.
Federal and State Layers
U.S. MSB registration and state money-transmitter licensing are distinct questions.
Licensed-Principal Route
Some businesses may operate through an approved Authorized Delegate or agent structure rather than owning every state license.
Banking Does Not Equal Licensing
An FBO account, named account, ACH access, or API does not independently authorize money transmission.
Core Design Questions
- Who is the legal account owner?
- Who is the economic owner of the funds?
- Who is the debtor and who is the ultimate debtor?
- Who is the creditor and who is the ultimate creditor?
- Are the underlying parties related companies or external customers?
- Which countries and currencies are involved?
- Which rails are required?
- What monthly volume and transaction count are expected?
- Is a named, virtual, pooled, FBO, or safeguarded account required?
- Who performs KYC/KYB, sanctions screening, and transaction monitoring?
- How will the internal ledger and reconciliation work?
What We Can Help With
We can help map the transaction, identify the appropriate banking/payment architecture, determine what type of provider is required, prepare the provider-facing flow of funds, and source or introduce suitable banks, PSPs, MSBs, or program partners where there appears to be a fit.
Frequently Asked Questions
Does POBO exempt me from MTL requirements?
No.
Is federal FinCEN registration enough?
No. State licensing analysis may also be required.
Related POBO / COBO Pages
- POBO & COBO Solutions
- POBO for PSPs, MSBs, and Payment Companies
- COBO for PSPs, Marketplaces, and Payment Platforms
- POBO & COBO Compliance: Ultimate Debtor, Ultimate Creditor, and Payment Transparency
- POBO & COBO Account Structures: Named, Virtual, FBO, and Pooled Accounts
Related Services
Get Help Designing This Structure
Send us your entity chart and flow of funds. If you do not have a diagram, describe who pays, who receives, who owns each account, what the underlying obligation is, and where the money ultimately goes.