
Part of our POBO & COBO Solutions guide.
The Problem
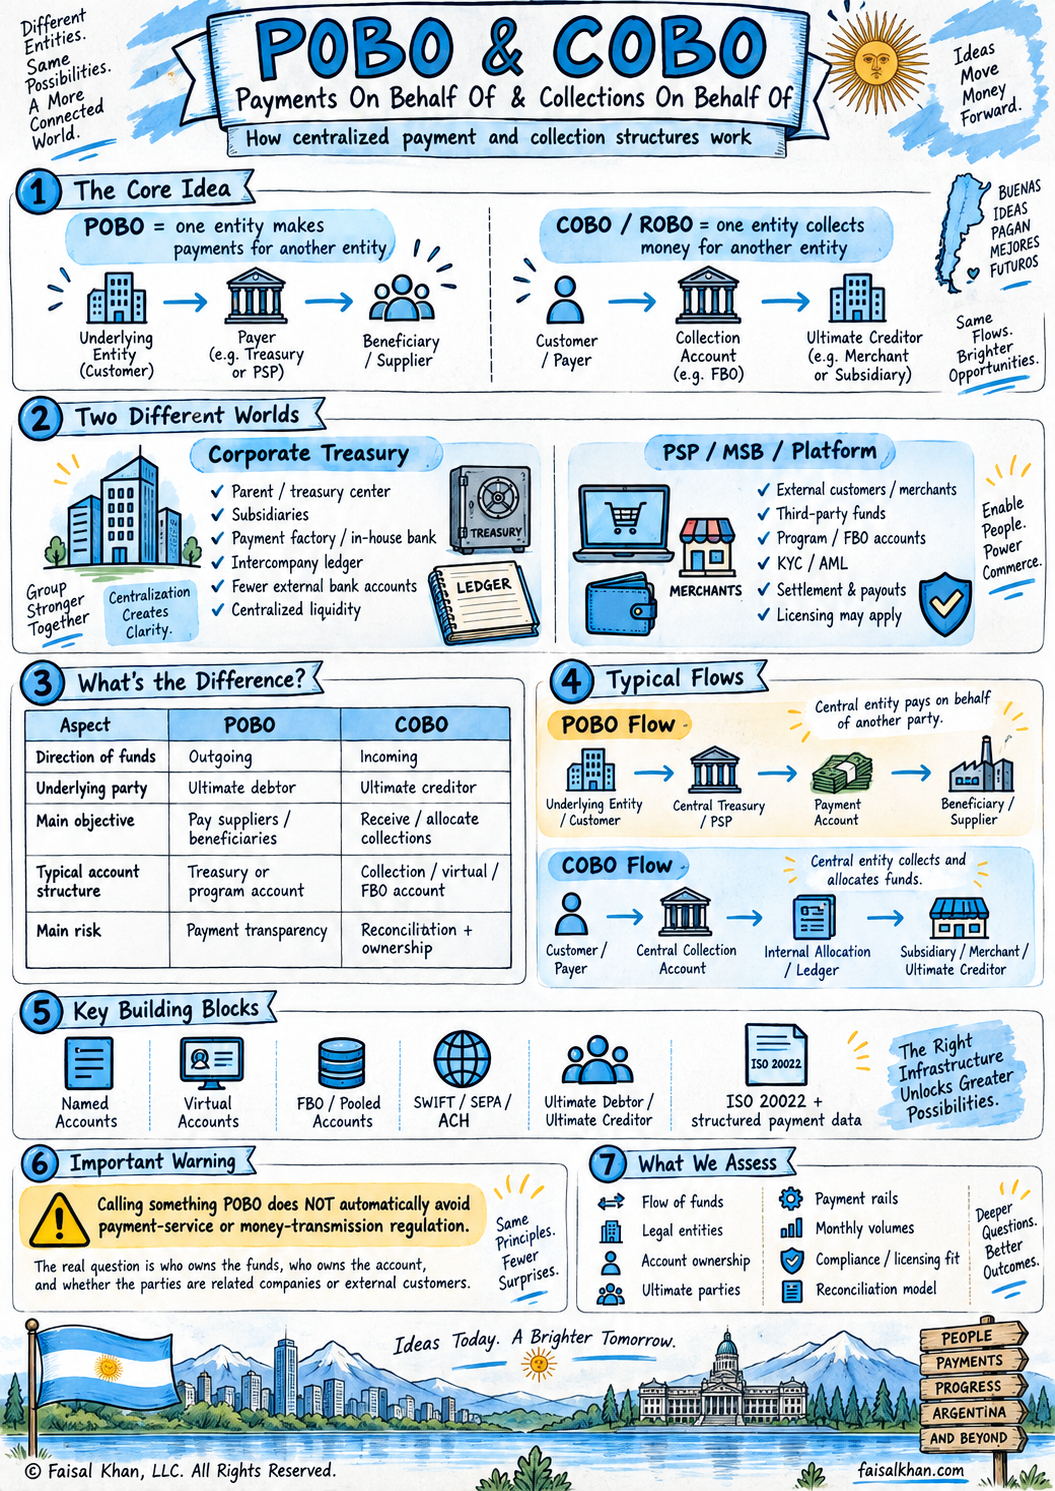
POBO and COBO are often discussed together because they centralize opposite sides of cash movement. POBO centralizes outgoing payments. COBO centralizes incoming collections. A group or platform may implement one without the other, or use both as part of an in-house-bank or regulated payment architecture.
The correct design starts with the flow of funds: who owns the funds, who owes or is owed money, who owns the external bank account, what the relationship is between the parties, and whether the underlying parties are related group companies or external customers.
Typical Flow
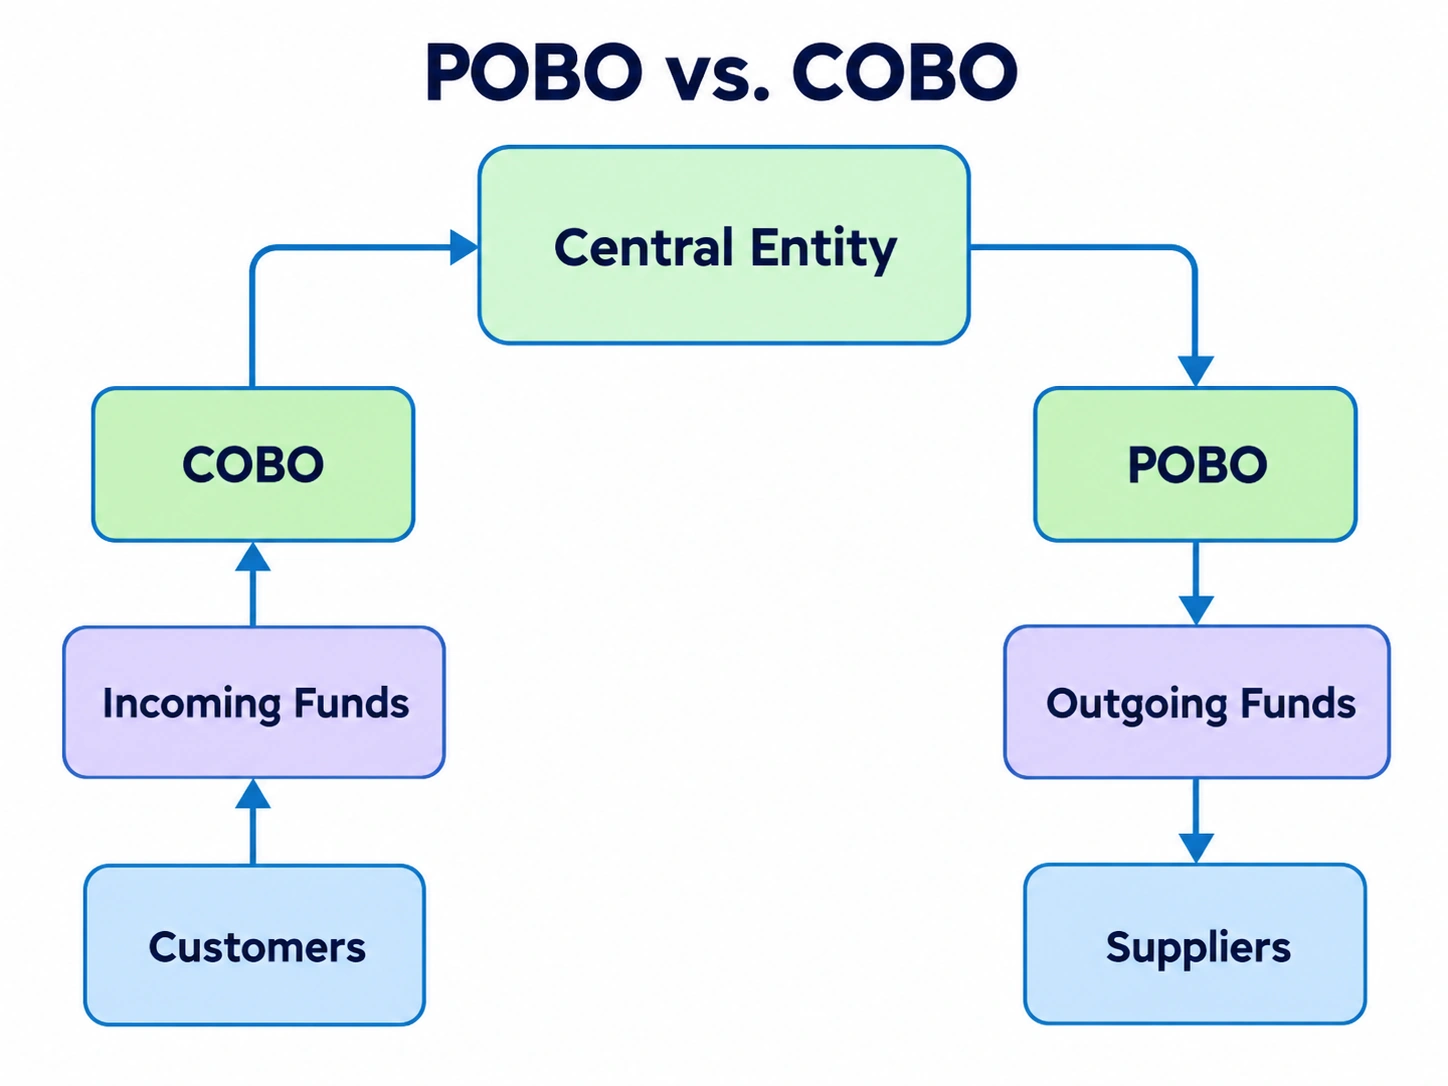
The diagram is intentionally generic. Actual implementation depends on the legal entities, jurisdictions, bank/provider rules, payment rails, currencies, licensing status, and reconciliation model.
Direction of Funds
POBO is outbound; COBO is inbound.
Underlying Party
In POBO, the key hidden relationship is usually the ultimate debtor. In COBO, the key hidden relationship is usually the ultimate creditor.
Can You Use Both?
Yes. Mature treasury centers and payment programs often centralize both collections and payments.
Core Design Questions
Who is the legal account owner?
Who is the economic owner of the funds?
Who is the debtor and who is the ultimate debtor?
Who is the creditor and who is the ultimate creditor?
Are the underlying parties related companies or external customers?
Which countries and currencies are involved?
Which rails are required?
What monthly volume and transaction count are expected?
Is a named, virtual, pooled, FBO, or safeguarded account required?
Who performs KYC/KYB, sanctions screening, and transaction monitoring?
How will the internal ledger and reconciliation work?
What We Can Help With
We can help map the transaction, identify the appropriate banking/payment architecture, determine what type of provider is required, prepare the provider-facing flow of funds, and source or introduce suitable banks, PSPs, MSBs, or program partners where there appears to be a fit.
Frequently Asked Questions
Which should I implement first?
It depends on the operational problem. Groups with fragmented AP may begin with POBO; groups with fragmented receivables may begin with COBO.
Are the bank-account requirements identical?
No. Collection structures often benefit from virtual accounts and reconciliation tools, while payment structures focus on payment authority, beneficiary data, and execution.
Can one central account do both?
Potentially, but providers, accounting, legal structure, currency needs, and reconciliation requirements must support it.
Related POBO / COBO Pages
Related Services
Get Help Designing This Structure
Send us your entity chart and flow of funds. If you do not have a diagram, describe who pays, who receives, who owns each account, what the underlying obligation is, and where the money ultimately goes.